Make Texture a preferred source on Google to support us
Add Texture to GoogleBehind the polished acetate of a pair of Ray-Ban frames and the clinical precision of prescription lenses lies a stock market equation of rare intensity. Long viewed as an unshakable bastion of European capitalism, EssilorLuxottica is facing a storm of unprecedented magnitude. Since November, the market capitalization of the Franco-Italian giant has plummeted by more than 55%. This spectacular bloodletting shatters the myth of the “core portfolio” stock—the one you buy and then forget about, convinced that demographics and global demand for eyewear guarantee a perpetual income stream. Today, the company is grappling with the reality of a market that has stopped buying into a narrative and is now demanding certainties—particularly amid the shifting landscape of new technologies and internal management dynamics.
This downturn didn’t come out of nowhere, but the severity of the decline has taken even trading floors by surprise. The recent drop of about 3%, which sent the stock plummeting to around 140.70 euros, has brought the company back to valuation levels not seen since 2022. Even more symbolic, this plunge makes the group the undisputed laggard of the Euro Stoxx 50 index this year. For an industrial player of this caliber, whose dominant position in the global optics market is mathematically unchallenged, such a discount signals a paradigm shift. Investors no longer value only the market share gained; they are assessing the execution risk associated with future promises.
“Wearable” technology: a gamble with an uncertain timeline
The crux of the problem lies precisely on consumers’ noses—or rather, on what the industry hopes to place there over the next decade: smart glasses. EssilorLuxottica has tied part of its narrative to Meta Platforms, hoping to transform this fashion and vision accessory into a cutting-edge digital device. The ambition is immense, but the timeline for its adoption is proving much more erratic than expected.
The evolution of Kepler Cheuvreux’s stance perfectly illustrates this volatility in expectations. Last January, enthusiasm reigned. The brokerage firm’s analysts had even raised their rating, buoyed by enticing sales projections. The trajectory seemed clear: from 2 million units sold this year, the market was expected to surge to 6.5 million units by 2025. This prospect of exponential growth justified a generous valuation premium at the time.
A few months later, the narrative changed radically. Kepler Cheuvreux downgraded its recommendation, shifting from a “buy” rating to a “reduce exposure” recommendation. The revision of the price target was drastic, with the estimate plummeting from 244 euros to just 135 euros. This reversal is not merely a technical correction; it reflects deep concern about the pace of development and profitability of this new product category. The smart glasses market, still in its infancy, requires massive investments in R&D and marketing, while adoption by the general public remains dependent on use cases that sometimes struggle to move beyond the stage of being mere gadgets or technological experiments.
The specter of governance
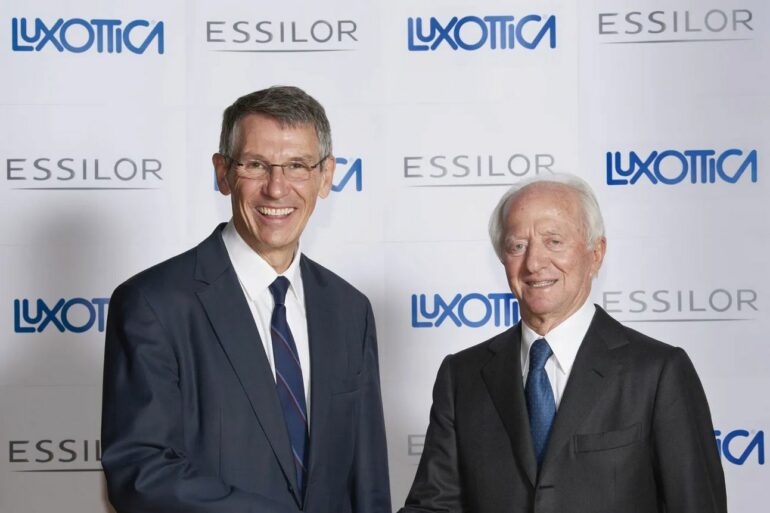
While the technological issue weighs heavily in the balance, it is not the only factor at play. Added to the doubts about Meta’s timeline are more structural concerns. Analysts point to persistent concerns about the company’s governance. During such a delicate period of strategic transition—one requiring Silicon Valley-level agility—the market is closely scrutinizing the decision-making apparatus’s ability to operate smoothly. When the stock rises, investors put up with internal complexities. When it loses more than half its value in a matter of months, even the slightest ambiguity in the chain of command becomes a reason to sell.
The coexistence of a centuries-old European industrial culture with the hyper-growth imperatives of the tech sector requires perfect alignment. The doubts expressed by some brokers suggest that this alignment does not provide all the guarantees of smooth operation that were hoped for, reinforcing the wait-and-see attitude of fund managers.
A Divided Consensus
Faced with this plunge, the financial community finds itself deeply divided, revealing a company with two faces. On one hand, there is Kepler Cheuvreux’s unapologetic pessimism. On the other, analysts who refuse to give in to panic. Bernstein Research, for example, maintains a neutral “Market-Perform” rating, while keeping its price target at 200 euros. This gap of nearly 65 euros between the two targets (135 versus 200) reflects the current difficulty in predicting the optical retailer’s trajectory.
The paradox reaches its peak when one looks at the general sentiment. Despite the stock market crash that began in November and its unenviable status as the worst performer on the Euro Stoxx 50, EssilorLuxottica remains, according to data compiled by Bloomberg, one of the European stocks with the highest overall ratings from analysts. The core business—the manufacture and distribution of traditional eyewear—continues to generate massive cash flows. No one disputes Ray-Ban’s market clout or the density of its global distribution network.
It is precisely this dichotomy that makes the current situation so complex. The financial markets do not question the group’s historical foundation; they simply refuse to continue paying in advance for the next chapter. The status of a “safe bet” is a thing of the past. It no longer protects against skepticism when promises of new growth drivers fall behind schedule or when the internal structure raises questions.
For now, the Franco-Italian leader is navigating a period of turbulence where the benefit of the doubt has vanished. The drop to 140.70 euros marks the end of a period of leniency. To regain confidence and bridge the gap that now separates its current valuation from its past highs, the group will have to do much more than rely on the strength of its brands. It will need to prove, quarter after quarter, that the merger of traditional eyewear with Meta’s technology can translate into tangible revenue, while dispelling the doubts surrounding its leadership.