Make Texture a preferred source on Google to support us
Add Texture to GoogleFor quarters on end, the executive committees of the global luxury industry have been scanning the Asian horizon, hoping to see the reassuring curve of a “U” take shape. That letter symbolized the promise of a sharp decline followed by an equally spectacular rebound in sales. The relentless reality today takes the form of an “L”—a steep drop followed by a prolonged period of stagnation. The mechanics of Chinese consumption, once considered an unshakable given, have ground to a halt. And with it, the entire economic model of the major fashion houses is faltering, faced with an economic climate where caution has supplanted euphoria.
This assessment stems from an in-depth analysis by Bernstein, and more specifically by Luca Solca, a keen observer of the sector’s dynamics. His diagnosis challenges established assumptions: a wait-and-see approach no longer has a place. The hope for a natural return to the happy days before the crisis now borders on wishful thinking. The time has come to scale back ambitions for the coming years, given that Chinese consumers’ mindset has shifted profoundly under the weight of a gloomy economic climate.
The End of a Thirty-Year Golden Age
To gauge the shockwaves of this slowdown, we must look back. Until 2019—and over a period spanning nearly three decades—the industry sailed on calm waters, posting a staggering annual growth rate of about 8%. This era of continuous expansion did not come about by divine intervention. According to data compiled by Bernstein, half—or even two-thirds—of this dizzying momentum rested solely on the shoulders of Chinese buyers.
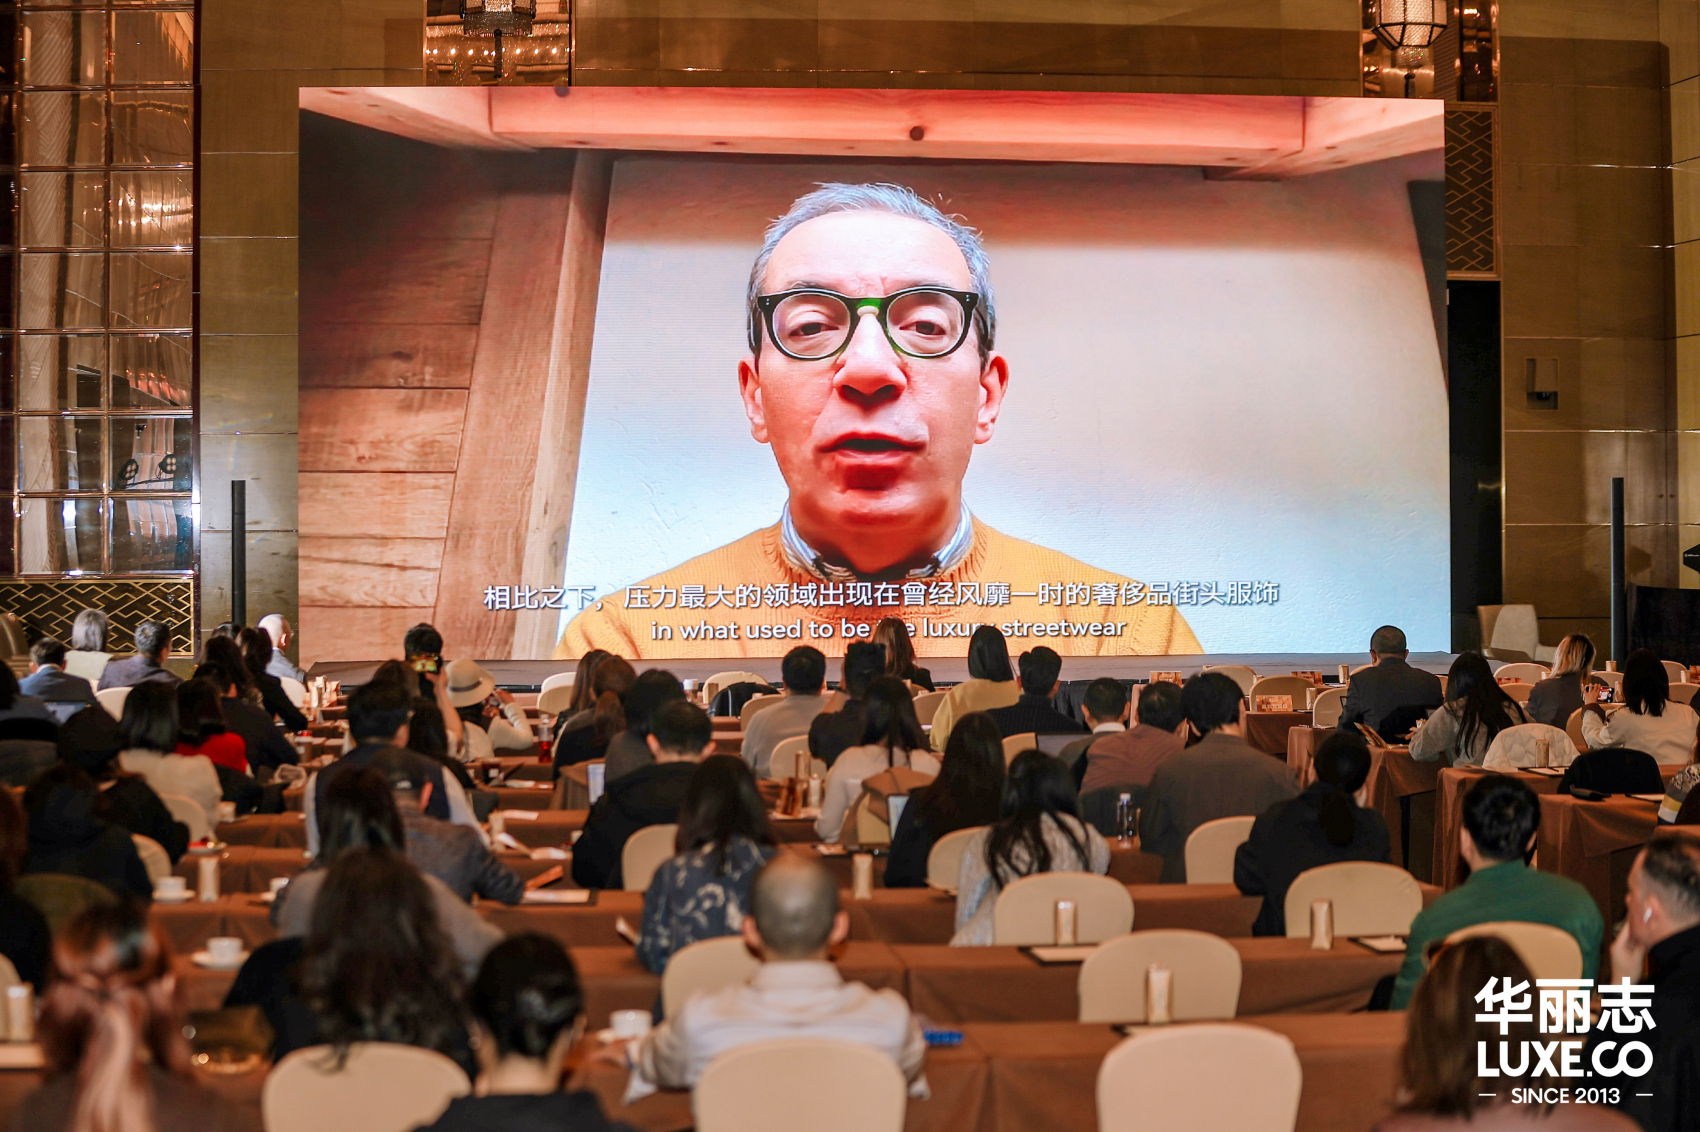
Today, the equation is reversing. Projections indicate that without a resurgence from this strategic clientele, the global sector’s growth rate would drop by half. Instead of the usual 7 to 8%, the market would have to settle for sluggish growth ranging between 4 and 5%. A sharp slowdown, especially considering that for some of the companies analyzed by analysts, China still accounts for between 15% and nearly 40% of global consumption. The dependence is such that a sneeze in Shanghai immediately sends a chill through global financial statements.
The Roots of Persistent Sluggishness
The wallets of China’s middle and upper classes have tightened, not out of a lack of appreciation for luxury, but under the pressure of a macroeconomic stranglehold. The report highlights the fracture in the country’s traditional pillars of wealth creation. Real estate, long viewed as a surefire social and financial ladder, is spiraling downward. Financial services, another engine of rapid wealth accumulation, are idling.
Compounding this decline in wealth is a generational anxiety. Unemployment is hitting young workers hard—the very same people who, until now, had been the ideal gateway for brands seeking to build loyalty among a new customer base. Even more worrying for the future of status-driven consumption is the looming shadow of automation. Spectacular advances in artificial intelligence and robotics pose a direct threat to office jobs and white-collar wages. Faced with this uncertain outlook, the natural instinct takes over. Families are no longer spending; they are hoarding. Savings are swelling, but money isn’t flowing into stores.
A Politically Outward-Looking Outlook
Against this backdrop of domestic stagnation, the sector might hope for strong intervention by the authorities—a major plan to stimulate consumption, for example. But Bernstein’s analysis dashes that hope. Beijing is not, for the time being, with its back against the wall. The national economy is being kept afloat by another engine: exports. As long as Chinese products continue to flow in massive quantities beyond its borders, the political pressure to restructure the economy around domestic demand remains low.
We should therefore not expect a dramatic government bailout to stimulate domestic spending. Barring a sudden and unforeseen deterioration in the overall economic climate, government support measures will remain limited: incremental, measured, and likely short-lived. The private sector is left to its own devices to solve the problem of sluggish demand.
The Taboo of Value for Money
This is where the real strategic turning point lies. While Chinese consumers refuse to open their wallets for exorbitant prices, they have not, for that reason, taken a vow of poverty or renounced the appeal of status symbols. The desire remains, but it has become more rational. Customers are shifting toward more affordable pieces. For industry players, the message is crystal clear: the “head-in-the-sand” strategy—which would involve maintaining sky-high prices while waiting for the storm to pass—is doomed to failure.
Brands must now venture into territory they have long snubbed: affordability. There is an urgent need to rethink the product mix to offer more accessible entry points. The challenge is daunting. How can they offer tangible market value and rationally justify the price paid, without undermining the aura of exclusivity and premium positioning that are the very essence of their identity?
Those that cling to their old pricing models and refuse to adapt their offerings face an immediate consequence: the loss of their customer base to more agile competitors. Growth in the coming years will no longer be dictated from European headquarters. It will be hard-won on the ground, by proving to Chinese consumers—who have become extremely discerning—that the product on offer is truly worth the financial investment it requires.