Make Texture a preferred source on Google to support us
Add Texture to GoogleThere is a staggering gap between the glamour of a brand name and the cold reality of a balance sheet. On paper, the luxury automotive industry has never seemed more powerful, towering above the giants of fashion and high-end leather goods. Yet behind the immaculate bodywork and the polished brand messaging, the financial machinery is creaking. Is the aura of a prestigious name enough to mask the flaws in a business model undermined by an imposed technological transition? The question looms with burning urgency for the Stuttgart-based automaker, whose status as the undisputed jewel of the European industry is now facing turbulence of rare intensity.
The Paradox of an Illusory Crown
Brand Finance’s latest report paints a seemingly triumphant picture for the year 2026: the German firm has reclaimed its title as the world’s most valuable luxury brand. With a valuation set at $35.2 billion, it can afford to leave absolute powerhouses like Chanel, Louis Vuitton, and Hermès in its rearview mirror. This flattering ranking, however, hides a major mathematical anomaly. This valuation represents a 15% drop compared to the previous year. The automaker is climbing the global rankings at the very moment its own profitability is beginning to erode significantly.
How can this resilience at the top be explained? The financial analyst points out that the company’s value rests less on its current margins than on extraordinary symbolic capital. Its clientele displays an almost irrational, rock-solid loyalty that acts as a shield against market volatility. In the world of high performance, this reputation constitutes an invaluable intangible asset. It allows the company to stay the course and weather drops in profits, as long as the product’s promise remains clear and cash flow does not dry up permanently. But this resilience has its limits: prestige may justify ever-higher prices, but it does not automatically guarantee comfortable margins at the end of the quarter.
The Stock Market Illusion vs. Industrial Reality
To understand the current impasse, we must go back to the fall of 2022. Driven by the Volkswagen Group, the brand’s initial public offering (IPO) seemed like a crowning achievement. The operation, described as a major transaction on a European scale, was intended to cement the automaker’s status as its crown jewel and, above all, raise billions of euros to finance the parent company’s massive transition to electric vehicles. At the time, the company embodied the perfect cash cow—the ultimate safety net that reassured executives in Wolfsburg with every earnings report.
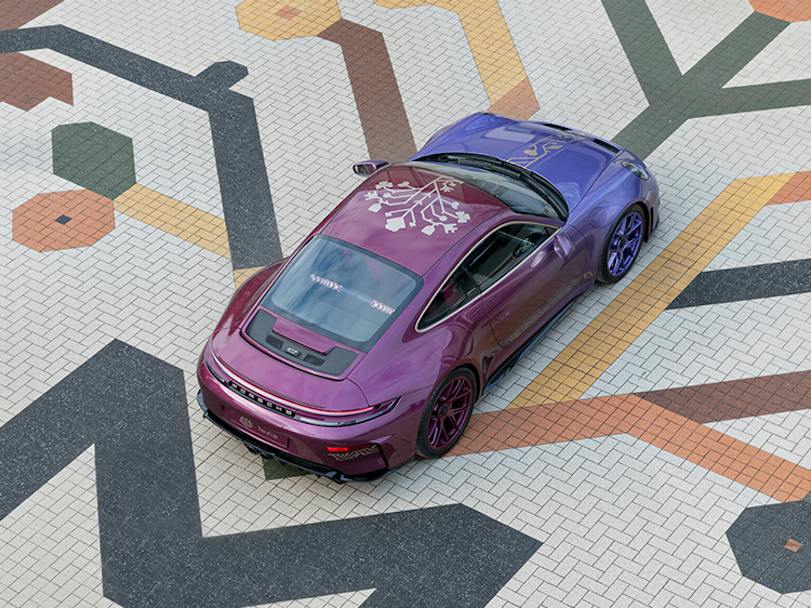
Four years have passed, and the euphoria has faded. The value of Volkswagen’s stake has plummeted. Worse still, internal reports and Reuters analyses reveal a symbolic affront that would have been unthinkable not long ago: the luxury brand’s profitability has fallen behind that of Škoda. The fact that the Czech division—a champion of pragmatism and volume—generates higher margins than the brand supposed to embody the pinnacle of engineering and exclusivity starkly illustrates the strain on the business model. The brand’s prestige remains intact in the public’s mind, but its financial foundations have become considerably weaker.
The Chasm in the Electric Equation
The crux of the problem lies in a transition timeline that is as inevitable as it is ruinous. The electrification of the lineup got off to a strong start with the Taycan and its Cross Turismo variant, before expanding to the electric Macan in 2024, and then to the Cayenne. Even the untouchable 911 has had to yield to hybridization, affecting the GTS and Turbo S variants. However, the industrial execution is sorely lacking in fluidity. The next generation of the 718 lineup is facing repeated delays, held up by technical architecture decisions that have yet to be finalized.
This trial-and-error process comes at a high cost, given that demand varies wildly from continent to continent. Data from CarBuzz reveals a clear divide: in the U.S. market, sales of the gasoline-powered Macan continue to far outpace those of its battery-powered successor. While global projections estimate that the electric version should overtake the gasoline version sometime in 2025, the transition remains a risky financial gamble. European regulations are forcing a rapid shift toward zero emissions, but customer demand does not always keep pace with regulatory constraints.
At the same time, the steady rise in sales prices over the past decade has not been enough to offset the pressure on production. The combination of U.S. tariff barriers, the prolonged slump in the Chinese market, and the colossal investments required by industrial restructuring has significantly inflated the final cost. Herein lies the paradox: cars have never been sold at such high prices, yet they cost infinitely more to develop.
The Shockwaves from the Parent Company
The company does not operate in an economic vacuum; it is bearing the full brunt of its parent company’s turmoil. Volkswagen no longer hides the scale of its own challenges. Faced with taxes in the United States and a sharp slowdown in new car registrations in China, the German group must orchestrate a massive reorganization. The German business press is reporting on particularly grim internal memos: thousands of jobs at risk, planned factory closures, and a drastic overhaul of the model lineup. The structural adjustment promises to be brutal.
In this hostile environment, the luxury automaker’s status has shifted dramatically. Once an invincible financial bulwark, it has become a source of concern for the Wolfsburg empire. It is amid this tense climate that Michael Leiters, recently appointed to take the helm and turn the company around, has been given a strict roadmap. The goal, leaked via Reuters, calls for a return to margins between 10 and 15 percent in the medium term. This is a very aggressive target given the current headwinds.
Admittedly, the completion of the Bugatti sale, scheduled for September 2026, offers Volkswagen some much-needed financial breathing room. But this surgical operation alone cannot cure the group’s deep-seated problems. Regulation, development costs, and geopolitics continue to weave a complex web that is squeezing the entire European industry.
A vital recalibration, free from nostalgia
The brand’s history proves that it knows the recipe for survival. At the dawn of the 2000s, the automaker came close to total extinction, suffocated by an obsolete lineup and exorbitant manufacturing costs. Salvation did not come from yet another brilliant marketing campaign, but from a ruthless operational overhaul and a refocus on concepts that would save the day: the decisive launch of the Boxster, followed by the gamble that was the Cayenne.
The challenge today requires repeating this feat of streamlining, but on a far more complex and costly playing field. Management must absolutely finance disruptive innovation while protecting the brand’s legendary aura and, above all, return to the profitability expected of a true luxury player. The stark contrast between the accolades bestowed by Brand Finance and the urgency described by financial analysts sums up the dizzying reality of the contemporary automotive industry: having the world’s most dazzling reputation no longer carries much weight if the financial engineering that underpins it threatens to collapse.