Make Texture a preferred source on Google to support us
Add Texture to GoogleA Milan showroom being sold off, stores to be closed, a headquarters to be relocated: at BasicNet, the integration of Woolrich is playing out far from the fashion collections. These decisions, less visible than the acquisitions, shed light on the Turin-based group’s financials. Over the first nine months of the year, sales rose sharply, but profits did not follow suit. The challenge, therefore, is no longer simply to expand the brand portfolio. It is to make a larger, more directly involved retail operation function effectively—one whose costs are already reaching a whole new level.
After the acquisitions, the work of selection
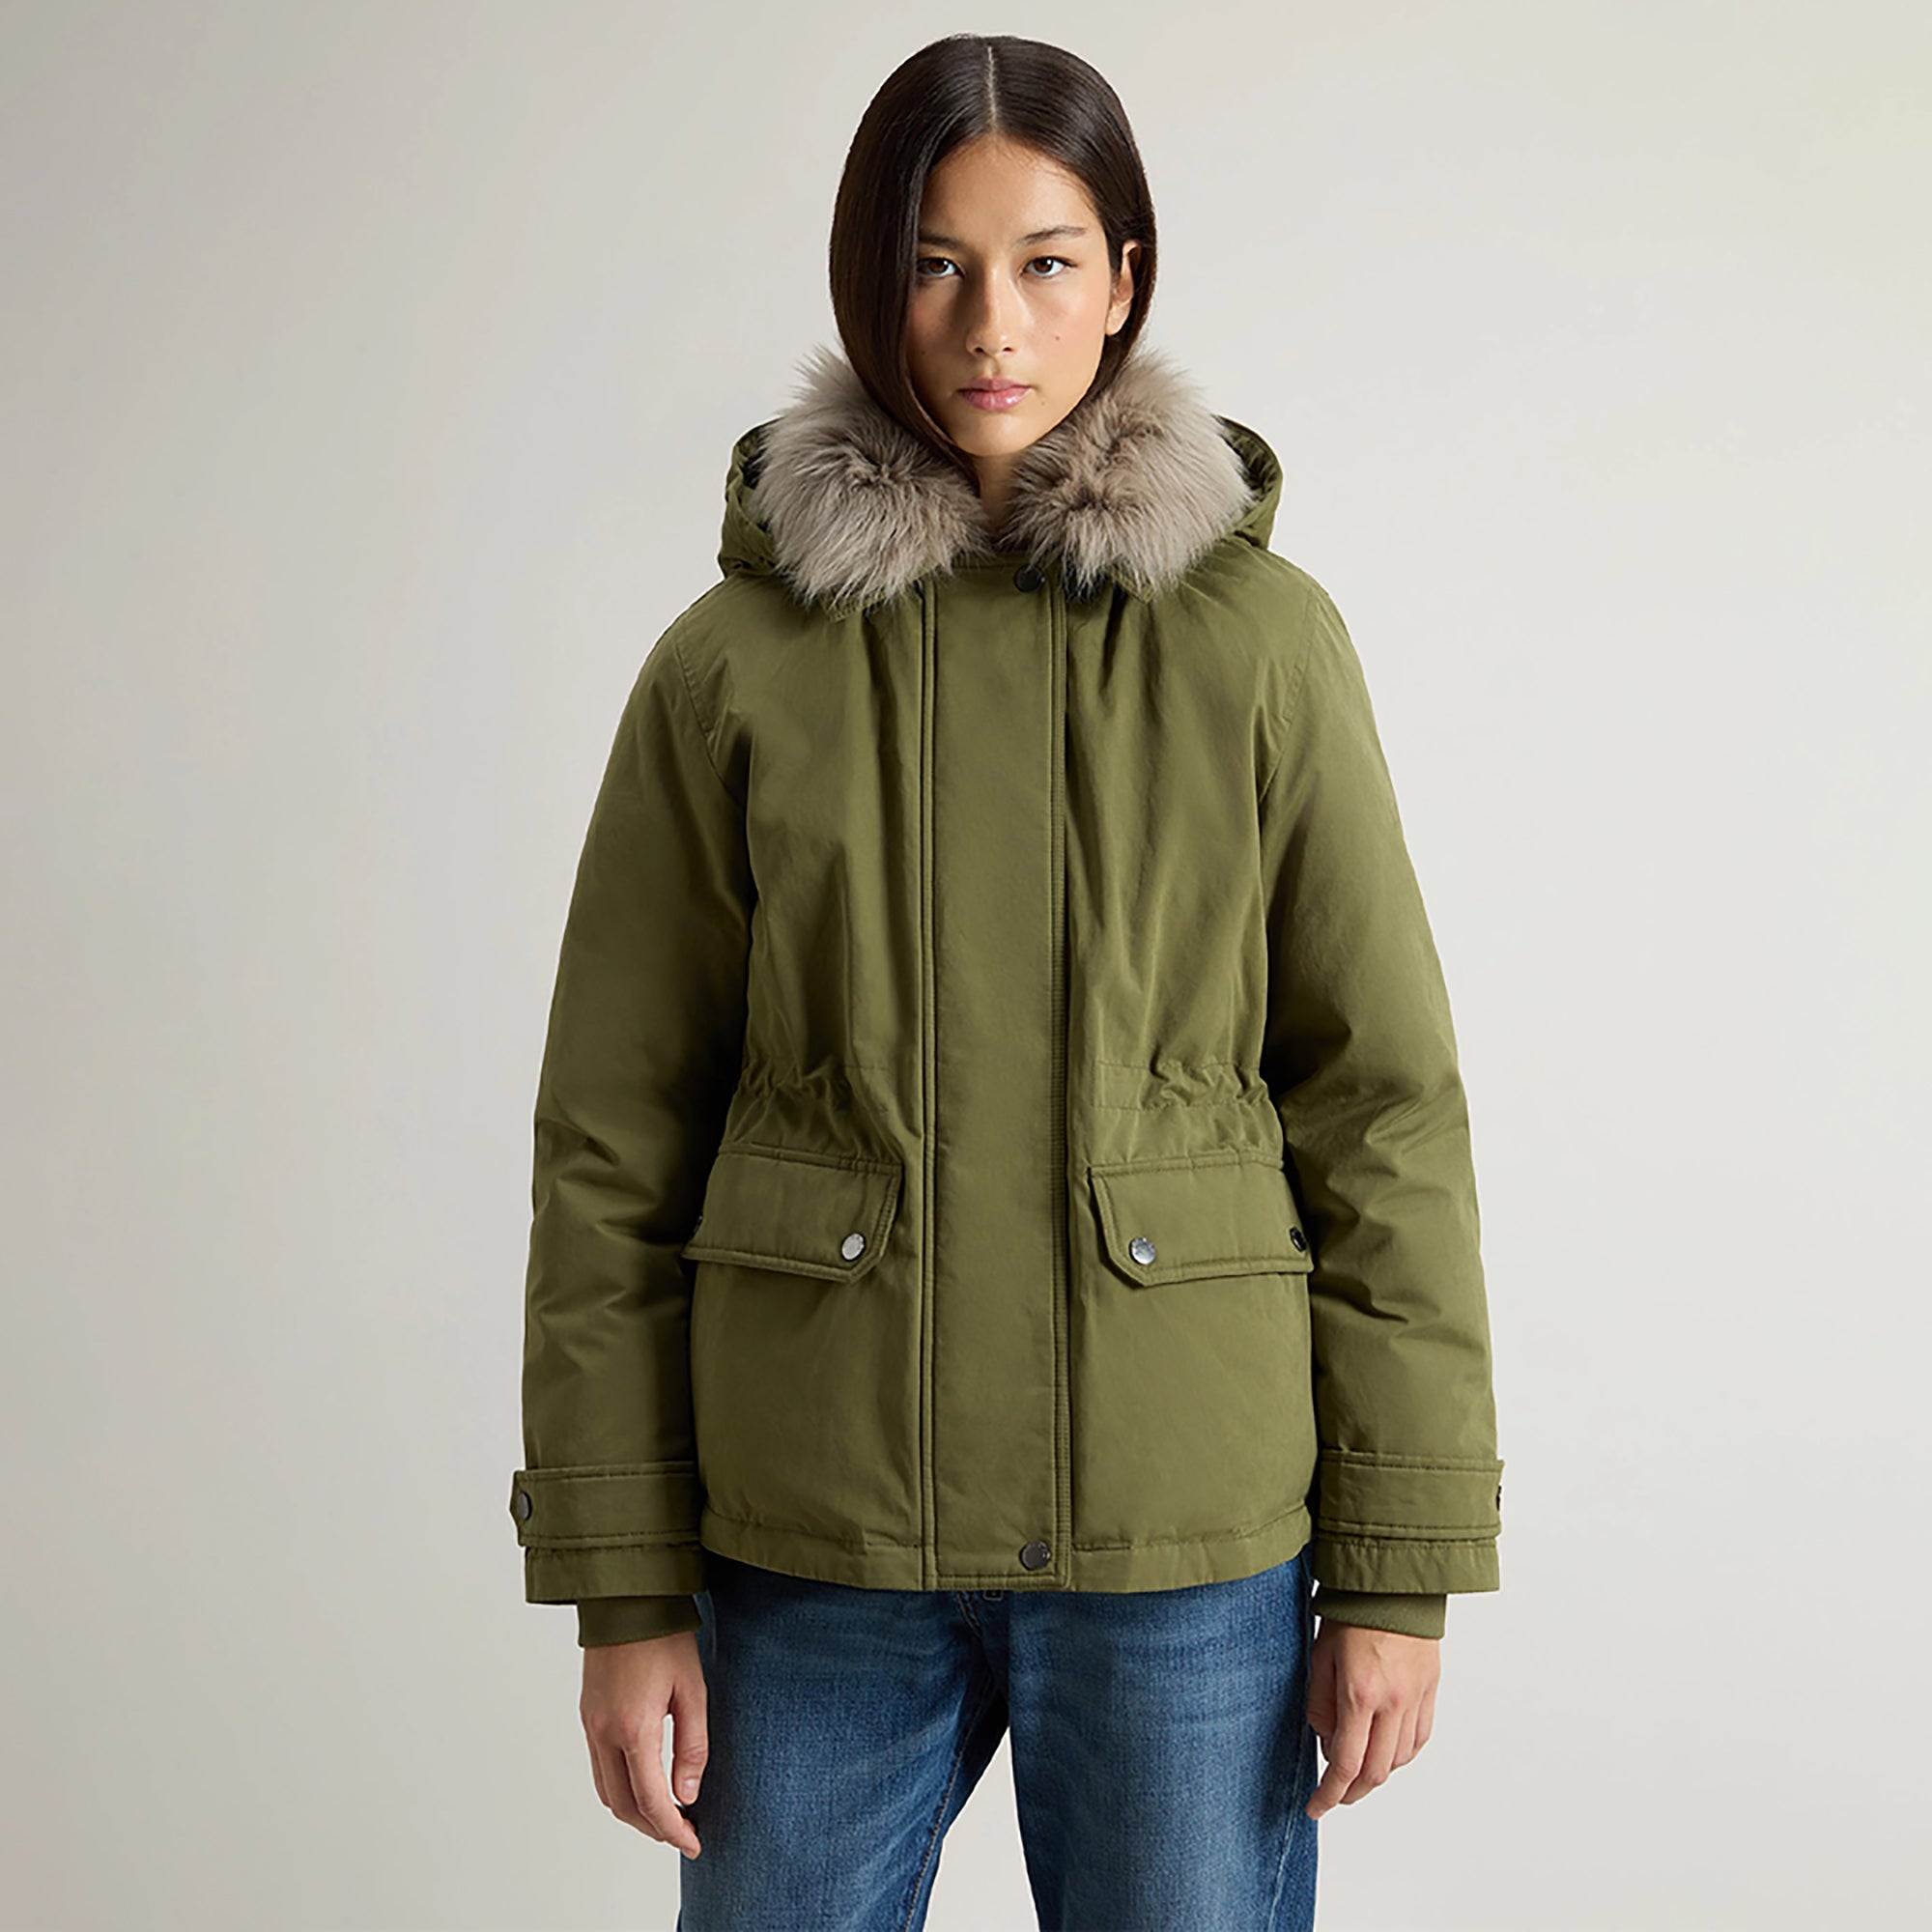
Woolrich and Sundek are now contributing to BasicNet’s growth. Their arrival is boosting sales, while also ushering in a period of adjustments whose impact is reflected in the financial results. Regarding Woolrich, the group mentions the gradual phasing out of operations deemed underperforming, including the Milan showroom and certain retail locations. The expansion of the business scope is thus accompanied by a process of streamlining: integrating a brand does not mean retaining every single location associated with it.
According to the company, these efforts are beginning to yield cost savings. The relocation of the corporate headquarters is also contributing to the announced efficiency gains. However, these positive effects coexist with €7.1 million in non-recurring exceptional expenses for the period. The overall outcome of the integration is therefore still mixed: the expenses have been recorded in the financial statements, while the operating benefits of the reorganizations are only beginning to show up there.
In its statement, BasicNet emphasizes a phased approach, against a backdrop of geopolitical and macroeconomic uncertainties. Brand enhancement and the creation of value over the medium and long term constitute its stated objectives. This is a way of viewing acquisitions over a longer timeframe than a single fiscal year. For the current financial statements, however, the issue is very concrete: how to absorb new businesses without letting their costs offset the growth they bring?
A distribution model that is changing the group’s profile
The answer lies in part in direct customer relationships. Direct sales totaled 327.4 million euros in the first nine months, representing a 29.6% increase compared to the period ending September 30, 2025. Woolrich and Sundek are driving this growth, alongside the gradual integration of European retail operations and the strong expansion of e-commerce.
These drivers are not interchangeable. The new brands are expanding the company’s scope; the consolidation of European operations and the growth of the digital channel are transforming how products are marketed. Consolidated revenue thus reached 369 million euros, an increase of 21.6%. This performance is therefore driven by several factors. It cannot be interpreted simply as an acceleration in sales within an otherwise unchanged business structure.
Conversely, royalties and supply commissions from third-party industrial and commercial licensees declined by 18.1%, to 40.8 million euros. The contrast is stark: direct sales are accelerating while this other source of revenue is contracting. Without signaling the end of the licensing model, the figures show a shift toward self-operated activities. This shift gives greater weight to the group’s sales network, but also to the resources needed to operate it.
Europe: The Driving Force and Focus
Geography offers another key to understanding the situation. Europe accounts for approximately 83% of aggregate global sales—a metric that combines direct sales with those of third-party commercial licensees. The region posted growth of 13.9%. Under these circumstances, strengthening the direct European presence amounts to investing more in the region that already accounts for the bulk of the business.
This concentration lends coherence to the distribution strategy. The integration of local operations, new store openings, and the pursuit of synergies between brands are being rolled out across BasicNet’s main market. It also makes the group’s trajectory particularly tied to that of Europe. The diversity of the regions covered should not obscure the highly uneven weight of each in terms of sales.
In total, aggregate global sales amounted to 745 million euros, up 11.5%. The Middle East and Africa also posted 11.5% growth, while Asia and Oceania remained broadly stable. The Americas, on the other hand, continued to decline, with a 19% drop. Growth is therefore not universal. And the 745 million euros should not be confused with consolidated revenue: it reflects the commercial activity of a broader group, including licensed partners.
Growth Weighed Down by Expenses
It is in the financial results where the gap with sales momentum becomes most apparent. EBITDA stood at 38 million euros, compared to 39.8 million at the end of September 2025. Despite the increase in revenue, this metric has declined. The 7.1 million euros in extraordinary expenses help clarify the comparison, without obscuring the tension between revenue growth and reported profitability.
Further down in the income statement, EBITA came in at 8.9 million euros, compared to 23.4 million in the corresponding period of 2025. The financial statements include 11.3 million euros in depreciation and amortization of tangible and intangible assets, as well as 17.8 million euros in amortization of right-of-use assets. The latter has more than doubled compared to 2025, primarily due to the expansion of the store network resulting from recent acquisitions and new store openings.
The expansion of company-owned stores therefore has a clear impact on the financial statements. The additional retail locations support the company’s commercial ambitions but also increase depreciation and amortization expenses. This is the ambivalence of this phase: the network intended to drive sales is already weighing on earnings. The cost savings from the Woolrich reorganizations are beginning to take effect in a context where expenses have, for their part, reached a new scale.
Expected synergies, a balance sheet already under greater strain
The financial situation adds another constraint to this transformation. The overall net financial position stands at −273.8 million euros, compared to −191 million as of December 31, 2025. The deficit has therefore widened significantly. Sales growth alone is not enough to demonstrate the strength of the trajectory: one must also consider the resources mobilized by the new scope of operations and the associated financial burden.
BasicNet now ranks the integration of Woolrich and Sundek into its business model among its top priorities, alongside strengthening its direct presence in Europe. The group also intends to develop commercial and operational synergies among its brands. The goal is clear: to ensure that the expanded portfolio functions as a coordinated whole, rather than as a collection of separate businesses whose costs would continue to accumulate.
The figures do not yet allow us to consider this effort complete. They show robust sales, cost savings that are beginning to materialize, and profitability that remains under pressure. The next challenge will be less dramatic than an acquisition: achieving greater efficiency from the existing network. At Woolrich, this has already taken a tangible form: the closure of the Milan showroom and certain underperforming stores.