One downward trend in Reformation’s results is worth noting: net revenue per customer in its direct-to-consumer channel declined by 1.4%. This doesn’t detract from the Los Angeles-based women’s brand’s growth, but it’s a detail that sheds light on how it works. Growth stems primarily from an expanding customer base, rather than from increased spending per customer. For this company, which recently went public on Wall Street, the challenge now is to continue this customer acquisition without sacrificing profitability. Its second-quarter financials show that it is succeeding so far. They also encourage us to look beyond the mere increase in revenue.
Customer Acquisition: The Engine of the Business Model
Direct sales are the cornerstone of Reformation. For the quarter ended June 27, they generated $135.3 million in revenue, up 21.2%. This figure far exceeds the $155.2 million in total sales reported by the company, or approximately 134.5 million euros. The direct-to-consumer model therefore remains critical to the brand’s trajectory.
The number of active customers in this channel increased by 22.9%. This is where the main driver lies: a broader customer base offsets the slight decline in net revenue per customer. The two metrics do not tell exactly the same story. The first indicates an ability to attract more active buyers; the second reminds us that this expansion was not accompanied, over the period, by an increase in individual contribution.
It would be an overreaction to interpret this as a sign of weakness. Direct revenue is growing significantly. But this distinction is important for assessing what comes next: maintaining this momentum will require either continuing to expand the customer base or seeing an increase in the revenue it generates. The results do not allow us to attribute the 1.4% decline to a specific cause. They do, however, allow us to identify what is currently driving sales.
Growth That Generates More Profits
Perhaps the most compelling figure is found further down in the financial statements. Net income reached $12.4 million, compared to $6.9 million a year earlier—a 79.4% increase. It is thus growing much faster than revenue, which rose by 24.1%. The additional business volume is therefore not being absorbed by expenses to the point of erasing the gain in profitability.
Adjusted EBITDA is following the same trend: it rose from $16.5 million to $25.4 million, a 53.9% increase. While this metric and net income are distinct, their converging trends highlight the strength of the quarter. Reformation is selling more and retaining a larger portion of its revenue as profit.
The reported data does not detail the drivers of this improvement. Based solely on these figures, it is impossible to isolate the role of costs or that of sales mix. CEO Hali Borenstein, for her part, highlights the flexibility of the merchandising strategy and the quality of operational execution. These are the management’s explanations; the financial statements, however, demonstrate profitability that accompanies growth rather than remaining merely a promise.
Wall Street inherits an already established momentum
The initial public offering gives this performance new significance. Reformation, in which the private equity firm Permira holds a majority stake, begins its life as a publicly traded company with a track record of continuity to its credit. According to Hali Borenstein, this second quarter marks the twenty-first consecutive quarter in which revenue has posted double-digit growth.
This consistency is just as important as any one-off acceleration. It allows the CEO to champion a long-term growth model rather than a single successful year. In her statement, she attributes this consistency to the strength of the brand and affirms her confidence in the company’s ability to continue profitable growth that creates value for shareholders.
This is the message of a company that must now make its trajectory clear to the market. Its appeal here lies in the combination of results: a growing active customer base, rising revenue across various channels, and accelerating profits. The caution remains just as valid. Twenty-one quarters do not guarantee the next one, and the acquisition of new customers will need to continue to yield measurable economic results.
France in an Expansion That Remains Very American
International expansion offers another point of strength. Revenue generated outside the United States surged by 36.8%, reaching $31.2 million. The expansion of the store network in France contributed significantly to this growth. The French market thus emerges as a recognized commercial driver, rather than merely a geographical presence for the brand.
Nevertheless, it is important to keep the proportions in mind. The United States generated $124 million in revenue during the period, up 21.3%. It remains, by far, Reformation’s largest market. International sales are growing at a faster pace, but from a much more modest base.
These two different growth rates indicate an expansion that is not based on replacing one growth driver with another. The U.S. market continues to grow while international operations are gaining ground. For France, no specific sales figures are provided. It is therefore impossible to measure its exact share of international revenue or to attribute the acceleration in growth solely to it. Its contribution is mentioned; its exact magnitude remains to be determined.
Other sales channels are gaining momentum
Given the dominance of direct sales, wholesale and other activities might seem secondary. Yet they account for the strongest growth among the channels presented: their revenue increased by 48.7%, to $19.9 million. Their volume remains lower than that of the direct channel, but their growth rate signals a broadening of revenue sources.
This trend qualifies the perception that growth is entirely dependent on retail stores and direct customer relationships. It does not overturn the model: the $135.3 million in direct revenue remains its center of gravity. It simply adds another pillar. However, grouping wholesale with other activities requires caution: the published figures do not allow us to attribute the entire increase solely to retailers.
A More Moderate Annual Outlook
For fiscal year 2026, Reformation forecasts revenue of between $602 million and $606 million, representing annual growth of 18.6% to 19.5%. This range is below the growth rate recorded in the second quarter. It sets a sustained growth trajectory without automatically extending the 24.1% increase observed during that period alone.
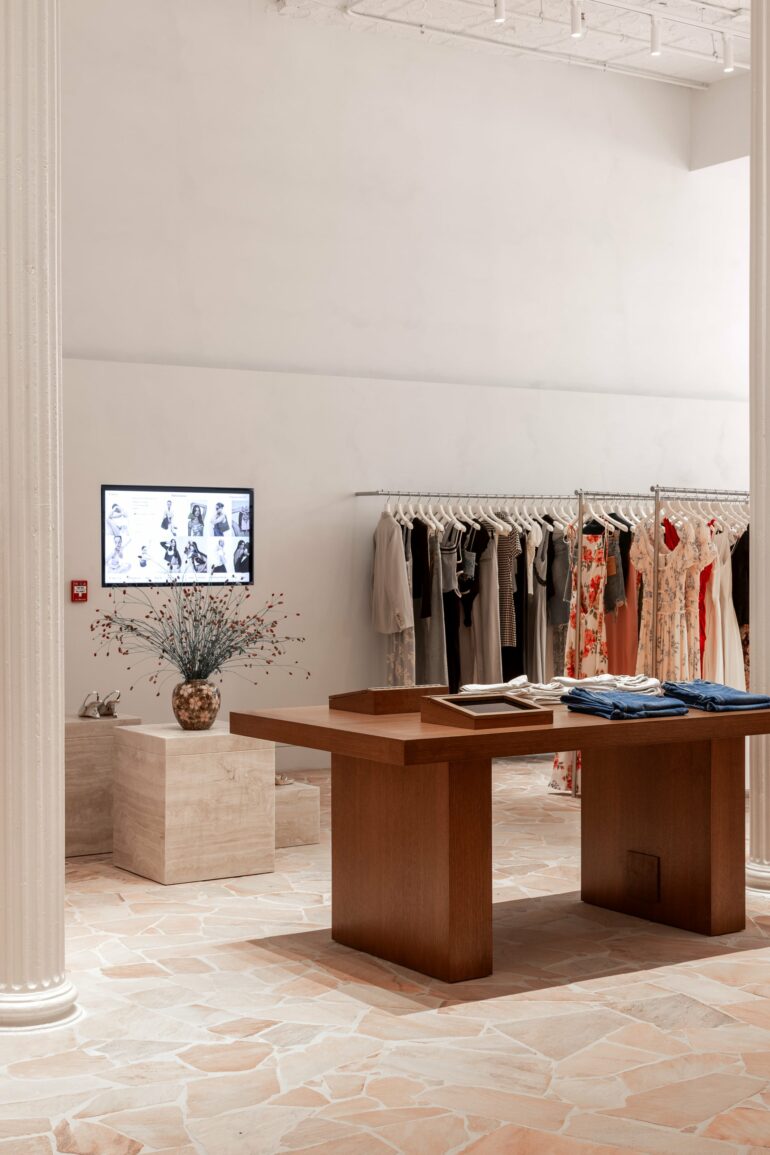
The brand currently operates approximately 70 company-owned stores. This network provides a tangible measure of its expansion, with France being one of its most recent markets. To assess the next phase, the number of locations alone will not suffice: it must be considered in conjunction with trends in active customers and the revenue generated by each. It is this interplay between market presence and customer contribution that the next financial reports will shed decisive light on.