Make Texture a preferred source on Google to support us
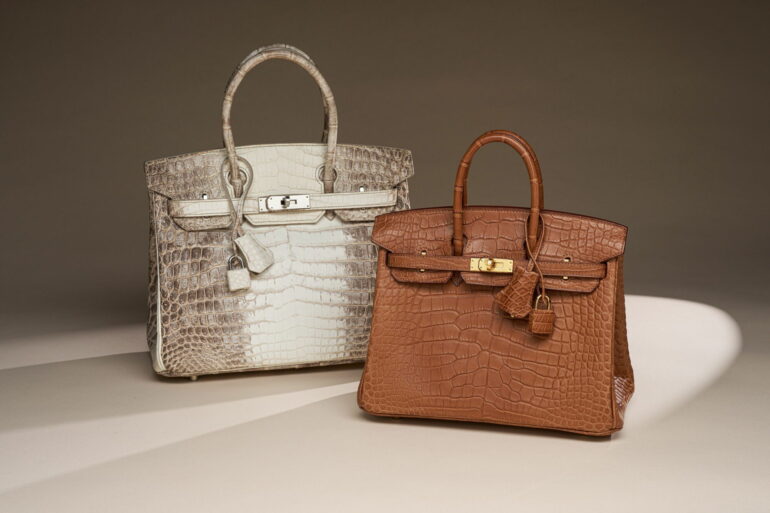
Add Texture to GoogleOne hundred million dollars. In the context of market capitalizations, international financial statements, and major mergers and acquisitions, this amount is almost within the margin of error. Yet, in the 2026 edition of the global study conducted by Interbrand, it marks a decisive shift in the hierarchy of sophistication and exclusivity. With a 10.6% increase in a single year, Hermès has raised its valuation to $45.2 billion. This upward momentum has allowed it to displace Louis Vuitton from the world’s fifteenth spot. The flagship brand of the LVMH group, facing an unexpected 6.9% decline, saw its value shrink to $45.1 billion. This development goes beyond a mere end-of-year battle over numbers; it crystallizes a paradigm shift for the entire luxury industry. By surpassing its historic rival, the house built on a culture of meticulously crafted leather, saddle stitching, and silk scarves has validated the triumph of a strategy rooted in tenacity and scarcity. A brand’s value is no longer measured solely by its geographic reach or its sprawling distribution network. Today, financial rewards are granted for unwavering consistency. While some players struggle against the wear and tear of constant overexposure and the shifting preferences of a highly volatile clientele, Hermès safeguards its desirability by transforming its raw prestige into sustainable growth. In this same vein of consolidation, Rue Cambon has regained a positive financial footing, with Chanel reaching a market valuation of $32.9 billion at the end of a period that observers deemed significantly more sluggish.
The Collapse of Brand Recognition as a Shield
Louis Vuitton’s decline is not an isolated case, but rather the muted echo of an upheaval that is hitting other sectors of the economy far more severely. The market appears to be undergoing a brutal correction, in which excessive visibility is backfiring on its own creators. In the sports apparel sector, the shockwave is of unprecedented intensity: Nike has suffered a staggering 35.5% drop, sending its market value plummeting to $21.7 billion. This backlash is hitting major apparel retailers and home furnishings giants just as hard. Adidas is down 7.9%, H&M has lost 12.1% of its value, while IKEA is down 13.5%. Brand equity proves highly volatile when competition boils down to a volume war. In saturated markets where consumer loyalty is melting away before our eyes, being known around the world no longer guarantees even the slightest competitive advantage against rivals.
This observation of fragility takes on historic proportions when examining the automotive industry’s performance. The sector stands out as the biggest casualty on the list. In the space of a dozen months, automakers have collectively wiped out $569.5 billion in market value. The magnitude of this contraction is altering the very landscape of the global economy, pushing the automotive industry behind the audiovisual and entertainment sectors. Toyota, although still comfortably seated on the throne of mobility with $59.5 billion, is experiencing a severe correction of 19.9%. The slide is sparing the flagships of German engineering even less. The premium segment of Mercedes-Benz and BMW is facing continued erosion, while Audi, Porsche, and Volkswagen are plunging into a deep slump, underscoring the loss of bearings in a market undergoing profound structural change.
Avoiding the Slump Through Style or Consistency
In this extremely turbulent environment for automakers, the Maranello-based company seems to be operating in a parallel dimension. Ferrari has claimed 51st place in the global rankings thanks to a spectacular 14.7% surge, bringing its valuation to $17.7 billion. The Prancing Horse is even one of the very few players to show an uninterrupted growth curve across the rankings. The explanation for this anomaly lies in a surgical strategic pivot: Ferrari has moved beyond seeing itself as merely a seller of sports cars to establish a truly global brand culture. Its ambitious yet meticulously controlled forays into the fashion world, the development of cutting-edge accessories, the monetization of its heritage through its museum spaces, and the signing of cross-brand partnerships have transformed the automaker. The company no longer sells performance on the road; it markets a highly exclusive way of experiencing the world of luxury.
Far from the exclusive and inaccessible price tags of haute couture, a different kind of rationality is triumphing in mass-market retail. An analysis of the figures reveals a fascinating trajectory for the leaders in fast fashion and leisure. Zara soars to $21.6 billion, securing 33rd place thanks to an 11.2% increase. Uniqlo confirms this appetite for well-designed clothing by securing the 38th spot with $20.5 billion (+16.2%). LEGO, the building-block manufacturer and a titan of home entertainment, climbs to 48th place with a 13.7% increase, bringing its total to $18.8 billion. Behind the diversity of their product lines, the formula for their success remains strictly the same. These giants offer the general public a reassuring model, built on consistent, predictable quality, strict control over their pricing policies, and a clearly defined geographic footprint. Where some have exhausted themselves by spreading themselves too thin, these players thrive on the promise of an offering that is immediately understandable across all regions.
Strategic patience and the imperative of utility
This premium placed on consistency also sheds light on the trajectory of Chinese conglomerates, which continue to advance their positions without the slightest media fanfare. In stark contrast to the theatrical communication sometimes favored by Western brands, the Asian industry is banking on a strategy of peaceful encirclement. Electronics specialist Xiaomi posted 12.6% growth, reaching $10.7 billion and securing the 75th spot. Battery and vehicle manufacturer BYD is patiently gaining ground with a 4.5% increase (8.5 billion, 89th place), closely followed by Huawei’s infrastructure division (+2.2%, 7.7 billion, 95th). These breakthroughs confirm a major trend: global dominance no longer requires high-profile publicity stunts; it is fueled by a slow, quiet, yet inexorable accumulation of market share.
The changing lineup of top players also demonstrates that public prestige does not hold a monopoly on power. Four entities have entered this financial elite: the insurer Zurich, the industrial group Hitachi, the medical technology expert GE HealthCare, and the IT division Hewlett Packard Enterprise. Their arrival on the front lines serves as a semantic wake-up call. Brand value does not measure the volume of applause from a captive audience, but rather assesses an organization’s cold, hard ability to transform an institutional identity into a source of sustainable revenue. Crossing the threshold into the top 100 brands now requires combining desirability with unwavering economic tenacity. Raw utility—rooted in risk management or hospital infrastructure—proves just as decisive as the dream.
The Optical Illusion of Digital Dominance
To grasp the true scale of these upheavals, one must inevitably look to the top of the pyramid, where valuations defy comprehension. The combined wealth of the world’s top 100 companies has surpassed $3,866 billion, marking an overall annual increase of 8.1%. Unsurprisingly, the tech sector sets the pace, accounting for nearly half of this financial mass. Apple dominates the landscape with a 9.3% increase, cementing its position with a valuation estimated at $514.6 billion. American dominance continues, with Microsoft ($443.7 billion) and Google ($389.3 billion) rounding out the top three, while Amazon remains in hot pursuit at $351.8 billion. The real stock market upheaval at the top of the list comes from Nvidia’s semiconductor business. With meteoric growth of 71.5%, the company has shattered all records to reach $74 billion, throwing open the doors to the top 10.
Nevertheless, this display of California’s leadership should not obscure the deep fissures in the global market. The economy is navigating unprecedented turbulence, where the veneer of century-old success begins to crack as soon as the ability to adapt falters. A prestigious name is no longer enough to guarantee favorable financial results. Clinging to a legacy without demonstrating tangible strategic transformation now results in a cold and definitive financial downgrade.