Make Texture a preferred source on Google to support us
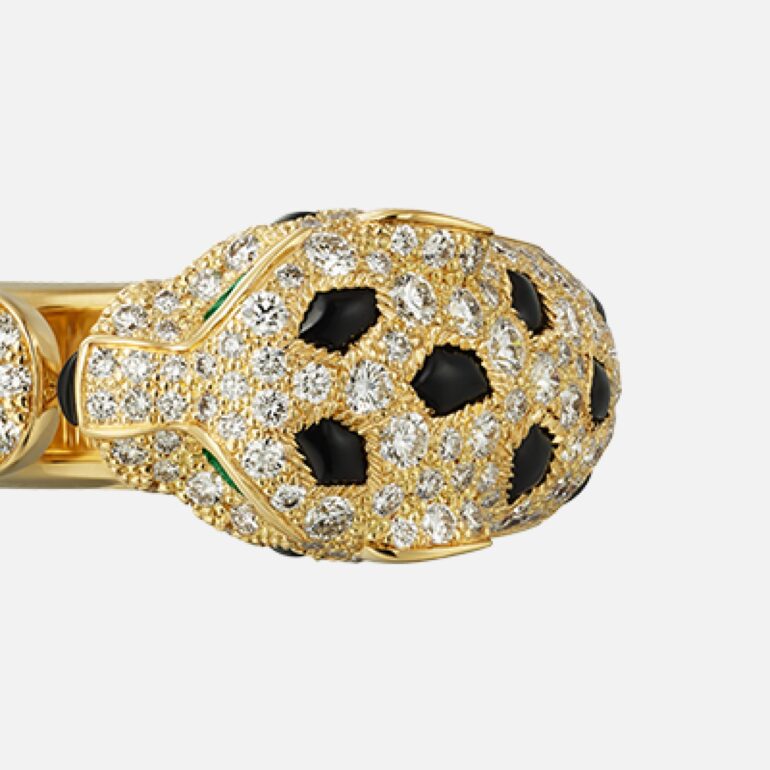
Add Texture to GoogleAt Richemont, the jewelry division generates more revenue than the entire group. The paradox is reflected in two figures: 3.2 billion euros in operating income for the jewelry houses, compared with 3.1 billion for all business segments combined. Cartier, Van Cleef & Arpels, Buccellati, and Vhernier thus account for far more than just the growth recorded in the half-year ended September 30, 2026; they are the driving force behind the group’s financial balance. Behind the sales growth, these financial results reveal a luxury sector operating at different speeds, where the strength of the jewelry segment contrasts with the still-modest recovery in watchmaking and the fragile profitability of other business segments.
Jewelry Sets the Pace
Of the 12.3 billion euros in half-year revenue, 9.2 billion came from the jewelry houses. Their business grew by 18% at current exchange rates and 19% at constant exchange rates, exceeding the 16% and 17% growth rates recorded by the group. This dominance gives Richemont a unique profile: the performance of just a few brands is enough to drive that of the entire portfolio, which also includes Vacheron Constantin, Alaïa, and Montblanc.
Profitability further underscores this concentration. Operating profit for the jewelry segment rose 27% compared with the 2.54 billion euros reported in 2025. Its margin reached 35.3%, or 33.4% after excluding non-recurring items. The second quarter remained strong, with sales up 15% at current exchange rates and 14% at constant exchange rates. However, the pace slowed compared to that of the first half of the year.
Gold is the other key driver of this success. Rising raw material prices—primarily for precious metals—are weighing on costs. Richemont has absorbed a large portion of these increases through price hikes and a more favorable sales mix. Jewelry remains a powerful driver of profits; however, its production is not immune to economic pressures.
Profitability Should Be Viewed Excluding One-Time Items
The consolidated financial statements therefore require two interpretations. The first is spectacular: operating income rose 33% at current exchange rates and 38% at constant exchange rates. The operating margin stood at 25.5%, a gain of 3.3 percentage points. Net income reached 2.5 billion euros, up 39%, while diluted earnings per share rose from 3.08 to 4.30 euros.
A second analysis excludes 229 million euros in positive one-time effects related to customs duties. Operating income then comes to 2.9 billion, for a margin of 23.6%. The improvement remains, but is limited to 1.4 percentage points. The same caveat applies to the gross margin: reported at 66.5%, up 1.2 percentage points, it would have declined by 0.7 percentage points without extraordinary items.
This distinction matters. Richemont is indeed improving its underlying performance, but the magnitude of the reported jump should not obscure the pressure on costs. Similarly, the 14% increase in sales in the second quarter, at current exchange rates, follows a 17% increase in the first quarter. As for the 6% decline in the stock price reported at the time of the earnings release, the available data does not allow for a specific cause to be identified.
The Boutique: The Commercial Center of Gravity
This jewelry business model relies on an increasingly direct relationship with the customer. Sales at the 1,395 boutiques operated by the group totaled 8.8 billion euros, representing 72% of its revenue. Their growth—19% at current exchange rates and 20% at constant exchange rates—significantly outpaced that of sales to distributors.
Online sales contributed an additional 726 million euros. Up 17%, it accounts for 6% of total revenue. Together, company-owned boutiques and digital sales bring the share of direct-to-consumer sales to 78%, two percentage points higher than a year ago. Sales through partners also grew, but by only 7%, to 2.75 billion euros.
This shift gives greater weight to spaces where luxury houses control the presentation of their creations and the customer relationship. In Richemont’s figures, the boutique is not merely a backdrop: it remains, by far, the primary point of sale.
A luxury landscape that is no longer limited to China
Regional trends shed light on this growth. In the Americas, revenue reached 3.2 billion euros, up 23% regardless of the currency conversion method used. The second quarter posted another 19% increase: this marks the eleventh consecutive quarter of double-digit growth in the region. This consistency sets the U.S. market apart from regions where the recovery remains tentative.
Japan, meanwhile, posted the highest growth rate at constant exchange rates: 30%, compared with 18% at current exchange rates, for 1.2 billion euros in sales. The discrepancy underscores how much exchange rates can alter the interpretation of performance. Europe grew by 12%, or 13% excluding currency effects, to 2.9 billion, with France and the United Kingdom standing out in particular.
In Asia-Pacific, revenue of 4.01 billion euros represents a 17% increase at current exchange rates and a 16% increase at constant exchange rates. But this average masks varying situations. Mainland China remains weak; China as a whole—including Hong Kong and Macau—grew by 7% at constant exchange rates. South Korea and Taiwan are performing better. Asian growth is therefore evident without masking China’s fragility.
The only region to see a decline, the Middle East and Africa, saw sales fall by 2% to 945 million euros. Regional conflict is affecting tourism spending, particularly in the United Arab Emirates. The second quarter accentuated this downturn, with a 7% decline at constant exchange rates.
The watch industry is regaining ground, though not to the same extent as the jewelry sector
Among specialized watch manufacturers, the improvement is evident in both profits and sales. Revenue reached 1.7 billion euros, up 9% at current exchange rates and 10% at constant exchange rates. Growth accelerated in the second quarter to 13% and 12%, respectively. Vacheron Constantin, Jaeger-LeCoultre, and A. Lange & Söhne led this growth.
Operating income tripled, from 50 to 150 million euros, but the margin remained at 8.8%, far below jewelry industry levels. In Asia-Pacific, watch sales were stable, held back by Chinese demand. Johann Rupert welcomed the growth that has been underway for over a year, while cautioning that the recovery could remain uneven.
The division encompassing fashion and accessories, Watchfinder, and components is, for its part, approaching breakeven. Its revenue rose 9% to 1.4 billion euros. Alaïa and Peter Millar posted double-digit growth, while Montblanc showed improvement. The operating loss narrowed to 12 million euros, compared with 42 million a year earlier.
Solid reserves, inventory to monitor
Richemont maintains net cash of 7.7 billion euros, after a dividend of 2.7 billion. Cash flow from operations rose to 2.5 billion, compared with 1.8 billion a year earlier. Inventories, however, reached 10.3 billion euros, up 649 million. Their inventory turnover improved, falling from 18.1 to 16.1 months.
In this environment, which Johann Rupert expects to remain volatile, the board is also clarifying its responsibilities. Appointed on September 9 as non-executive co-vice chairman alongside Bram Schot, Anton Rupert will oversee the strategic committee responsible for product and communications across the brands. Schot will be responsible for the governance of the board and its committees. This division of responsibilities explicitly places creativity and storytelling among the key priorities monitored at the group’s highest level.