Make Texture a preferred source on Google to support us
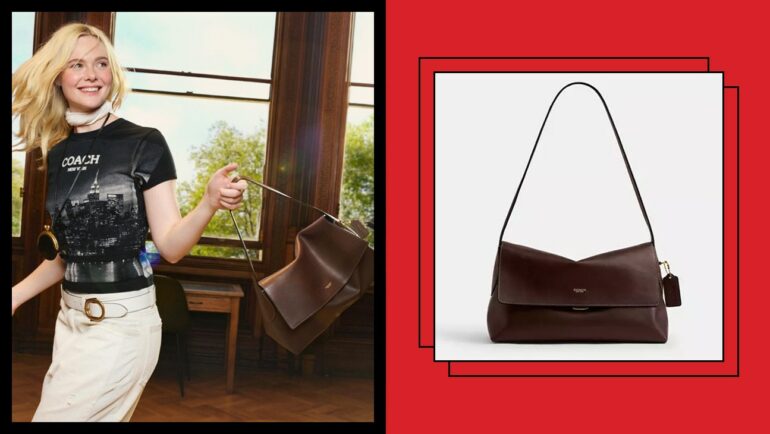
Add Texture to GoogleAt Coach, the average price of handbags is rising faster than the volume of sales. This is undoubtedly the most revealing detail in Tapestry’s results: a double-digit increase—at the lower end of that range—for the first metric; a rise of a few percent for the second. The brand is thus managing to sell more while significantly raising its average price. For its parent company, which also owns Kate Spade New York, this equation is driving rising profitability. It also reveals a dependency: behind the group’s strong numbers, Coach is almost single-handedly driving the growth.
Coach Sets the Pace, While Kate Spade Is Still Finding Its Footing
The two brands are not experiencing the same start to the fiscal year. With $1.66 billion in sales in the first quarter of fiscal 2027, Coach posted a 16% increase, identical at both current and constant exchange rates. Kate Spade New York saw a 10% decline to $233 million. The gap goes beyond a mere difference in scale: it underscores just how unbalanced the commercial momentum within the portfolio remains.
Ending on September 26, 2026, this quarter brought Tapestry $1.89 billion in revenue, or 1.70 billion euros based on the provided conversion rate. The increase reached 11%, with no overall impact from currency fluctuations. Excluding Stuart Weitzman, which was sold on August 4, 2025, growth on a comparable basis stands at 12%. This narrowed scope provides a clearer picture: Coach’s performance more than offsets Kate Spade’s decline, though it does not entirely eliminate it.
The rise in the average price of Coach handbags therefore warrants closer attention than total sales alone. It is accompanied by growth in volumes, albeit modest: revenue is thus not driven solely by a pricing effect. However, the published data does not allow for a precise distinction between what is attributable to pricing and what is due to the mix of purchases.
Generation Z is entering the market, and physical stores remain crucial
Another figure worth examining closely: Tapestry reports having recruited 2.6 million new customers in three months, approximately 35% of whom belong to Generation Z. This growth applies to the group as a whole. While this alone does not fully explain the performance of each brand, it provides a concrete measure of their collective ability to expand their customer base.
Joanne Crevoiserat, CEO of Tapestry, attributes these results to the Amplify strategy. In her presentation, she emphasized that creativity and craftsmanship must go hand in hand with the value offered to consumers. She also highlighted the importance of customer insight, data analytics, and the resources of an international group. Marketing is receiving increased attention: as a percentage of revenue, marketing investments have risen by 140 basis points.
However, brick-and-mortar retail remains central to this growth strategy. On a comparable basis, direct-to-consumer sales rose by 9%. Store sales are growing at a low double-digit rate, compared with a mid-single-digit increase for digital sales. As of September 26, Coach operated 983 company-owned stores, following fifteen openings and five closures during the quarter. Kate Spade operated a total of 318 stores, with eight closures. The retail networks are also evolving in different directions.
China is gaining momentum, while currency fluctuations are weighing on Japan
Geography offers a second perspective on Coach’s strength. For the brand, sales rose 7% in North America and 30% internationally, on a comparable basis and at constant exchange rates. Expansion beyond its primary market is therefore a powerful growth driver.
At the Tapestry level, however, North America remains the foundation: $1.11 billion in revenue, up 4%. Greater China is growing at a completely different pace, with $385 million in revenue and a 43% surge, which translates to 39% growth excluding currency effects. Europe reached $151 million, up 20%, or 22% at constant exchange rates.
Japan serves as a reminder of how much currency exchange rates can alter the perception of a market. Its sales of $103 million declined by 5% in the published financial statements but increased by 4% at constant exchange rates. In other Asian countries, revenue reached $114 million, up 26%, or 23% on a constant-currency basis. This international growth also bolstered sales to third-party distributors, which rose by approximately 30%—significantly more than the direct channel.
Profitability on the Rise Despite Marketing Efforts
Sales growth is reflected in the margins. Gross profit reached $1.49 billion, up 14%, and represented 78.6% of sales—2.3 percentage points higher than a year ago. On an adjusted, non-GAAP basis, this margin stood at 78.7%, an improvement of 2.2 percentage points.
A breakdown of this improvement shows that it cannot be attributed solely to the desirability of the products. Operational improvements contributed approximately 1.3 percentage points, the net favorable impact of customs duties and tariffs added 0.7 percentage points, and currency effects contributed 0.2 percentage points. At the same time, adjusted selling, general, and administrative expenses accounted for 55.5% of revenue, down slightly by 0.1 percentage points despite additional marketing investment.
Reported operating income rose 29% to $424 million, representing a margin of 22.4%. On an adjusted basis, it reached $439 million, or 23.2% of sales. The difference corresponds to $15 million in distribution optimization expenses, primarily related to the transfer of the logistics center from Ohio to a third-party-operated facility in Pennsylvania. Reported net income rose from $275 million to $360 million.
Shareholders Rewarded, Cash Flow to Watch
Tapestry is translating this confidence into substantial distributions. Approximately $700 million was returned to shareholders during the quarter, including $600 million used to repurchase some 4.6 million shares at an average price of $130. For the full fiscal year, the group is raising its capital return target to $2 billion. Share buybacks are expected to account for $1.7 billion of that total—$350 million more than previously announced.
The cash flow statement warrants a separate analysis from the income statement. Cash flow from operating activities rose from $113 million to $197 million, but adjusted free cash flow fell from $103 million to $56 million. Cash and cash equivalents totaled $782 million, compared with $2.56 billion in financial debt. Inventories rose slightly to 1.06 billion, compared with 1.02 billion a year earlier. The increase in profits therefore did not translate, over these three months, into a corresponding increase in all cash flow metrics.
Raised Targets, on a Clear Timeline
The group is now targeting annual revenue of between $8.5 and $8.6 billion, up from the previous range of $8.4 to $8.5 billion. This corresponds to growth of 6% to 7% at constant exchange rates. The expected improvement in the operating margin doubles, from 0.5 to approximately one percentage point. As for adjusted earnings per share, the new range of $8.25 to $8.35 replaces the previous range of $7.80 to $7.90.
These forecasts are based on 52 comparable weeks. The 53rd week of the fiscal year, which is excluded from this outlook, is expected to add approximately one percentage point to revenue growth. Before this calendar-related boost, the next milestone will be the second quarter: Tapestry expects sales growth of 5 to 6 percent, excluding currency effects, and earnings per share of approximately $3.05. This represents a more moderate pace of growth compared to the start of the fiscal year, which will provide an initial gauge of whether Coach’s momentum is continuing.